You saved for decades. Don’t give more of it to taxes than you have to.
Atwood Capital Management helps people approaching or in retirement invest their money, plan their taxes, and turn their savings into income.
The questions that come up as retirement gets closer
Will taxes take a bigger bite in retirement than I expect?
Should I convert part of my IRA to a Roth? How much, and when?
How will required distributions affect my taxes and Medicare premiums?
What happens to my spouse’s taxes if I die first?
Which accounts should I draw from first?
How much can I safely spend each year?
If these sound familiar, we can help.
The hidden cost of doing everything right
Decades of contributing to a 401(k) or IRA can leave you with a large tax bill in retirement. It tends to show up in three ways.
Withdrawals are taxed as ordinary income
Money leaving a traditional 401(k) or IRA is taxed at ordinary income rates, however it was invested.
Required distributions arrive on schedule
Eventually the IRS requires withdrawals each year, whether you need the money or not. That can push you into higher brackets and raise your Medicare premiums.
A surviving spouse often pays more
After one spouse dies, the other usually files as a single taxpayer, with narrower brackets on much the same income.
The early years of retirement are often the best time to act. After that, it usually costs more.
Every tax strategy we use comes down to three moves
Converting income from one type to another
Turning ordinary income into capital gains, qualified dividends, or tax-free Roth growth.
Shifting income from one pocket to another
Moving income to where it’s taxed least: a different state, account, or person.
Shifting income from one time period to another
Recognizing income in the years it’s taxed least.
How we help

Investment management
We invest your savings in diversified, low-cost funds built around your income needs and tax plan.

Tax planning
We plan what type of income you receive, which pocket it lands in, and when it’s taxed, years in advance.

Retirement income planning
We create a clear, sustainable plan for turning your savings into income, coordinated with Social Security and any pension.
We coordinate with your CPA so your tax plan and tax return work together.
Explore services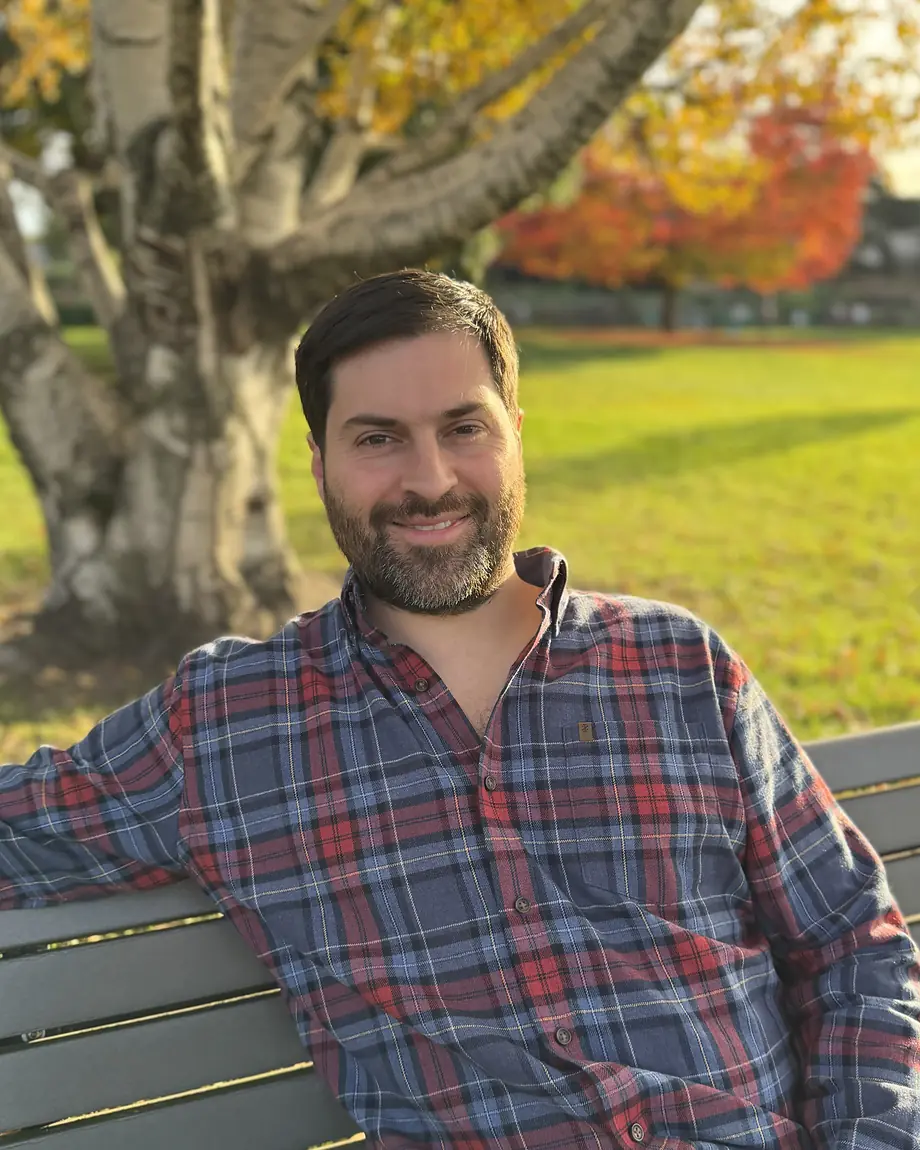
Meet Michael Labbe, CFA
Michael founded Atwood Capital after seeing smart, successful people save and invest diligently for decades while giving little thought to taxes.
Before founding the firm, he spent eight years in investment research, corporate real estate, and investment banking. He works directly with every client.
Read about MichaelA straightforward process
Free review
We start with a phone or video call to look at your accounts, income, and tax picture. You’ll leave knowing whether a multi-year tax plan makes sense for you, whether or not we work together.
Your plan
We build your plan for investments, taxes, and retirement income and walk you through it, including the trade-offs, by phone, by video, or in person.
Ongoing implementation
We manage your portfolio, implement conversions and withdrawals, and update the plan as tax law and your life change.
You may be a good fit if…
 You’re retired or within about ten years of retiring
- You have roughly $1 million or more in investable assets
- Taxes are one of your largest expenses, now or in retirement
- You want a plan implemented for you, not just a report
Transparent pricing
per year of assets managed, billed quarterly in arrears. On $1 million, that’s $10,000 a year. As a fee-only fiduciary, we’re required to act in your best interest, and we never earn commissions or sell products.
Find out where you may be overpaying in taxes
The review is free, there’s no obligation, and we meet by phone or video.